Get 60% Off QuantVPS: https://go.quantvps.com/TDDVPS
When you use this QuantVPS code you get 3 free indicators, a TDD CVD Divergence 2.0 AutoTrader Workspace, and 5 pre-loaded Strategy Templates to fit your trading style.
Claim 60% Off QuantVPSMechanize your edge with pure order flow divergence.
On this page - TDD CVD Divergence 2.0 AutoTrader and TDD CVD Divergence VWAP AutoTrader
When you use this QuantVPS code you get 3 free indicators, a TDD CVD Divergence 2.0 AutoTrader Workspace, and 5 pre-loaded Strategy Templates to fit your trading style.
Claim 60% Off QuantVPSRunning profit and loss for every strategy template.
| Ticker | Data Series | Strategy Template | Daily Profit / Loss | Performance Since Inception | Max Drawdown |
|---|
Results shown for the TDD CVD Divergence 2.0 AutoTrader strategy templates. Trading futures involves substantial risk of loss. Past performance is not necessarily indicative of future results.
No guesswork. No endless tweaking. Get up and running instantly with our comprehensive, step-by-step user guide. Includes exact, battle-tested settings for major instruments so you can start trading with confidence on day one.
Unlock the secret to passing evaluations and keeping funded accounts. This fully complete strategy guide reveals the exact sizing, risk-management, and scaling rules required to conquer strict drawdown limits.
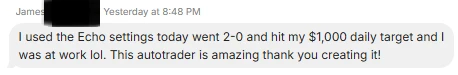
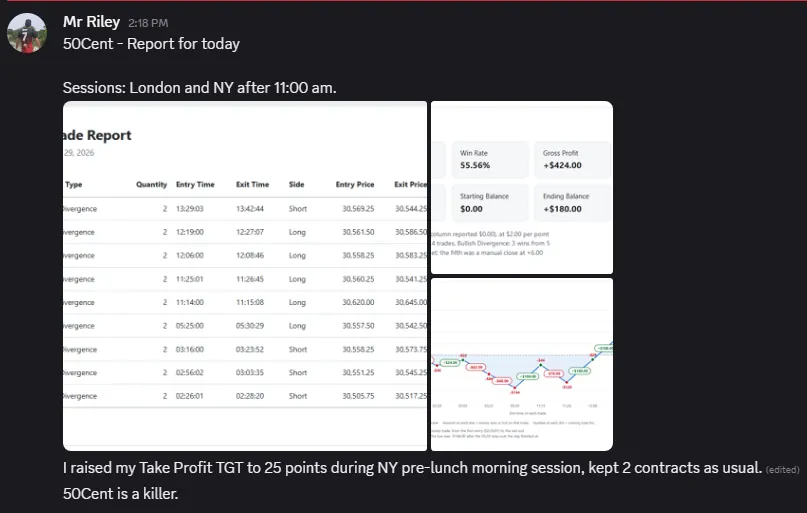
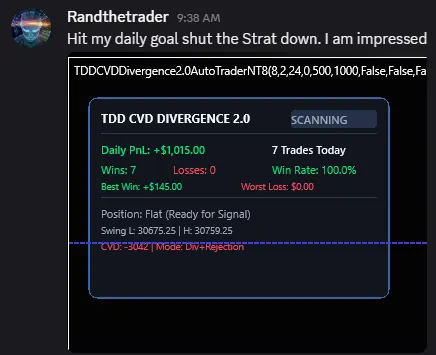
See real results from the Tactical Data Desk community. Our members are leveraging the Auto Traders to secure funding and build consistent profit.
Spot hidden absorption and mechanize reversals.
Retail traders constantly buy the top and sell the bottom because they can't see the order flow. They get trapped by institutional spoofing and fake breakouts.
The CVD Divergence Auto Trader tracks real-time Cumulative Volume Delta against price. It spots the exact moment aggressive volume dries up and institutions begin absorbing orders. When the divergence confirms, it executes.
No more hesitation. The Auto Trader calculates the divergence, measures the delta difference, and fires the trade based on your strict risk parameters:
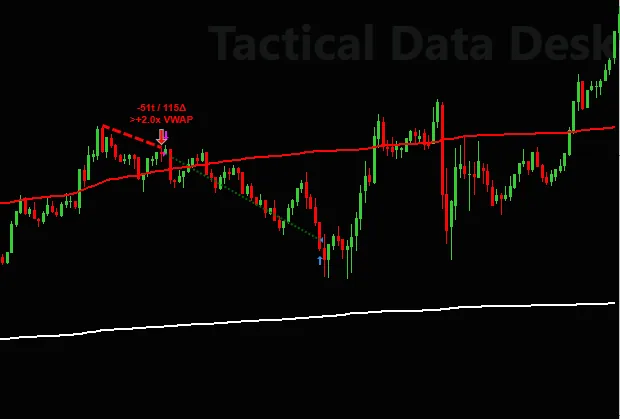
Watch how the AutoTrader spots absorption and mechanizes reversals.


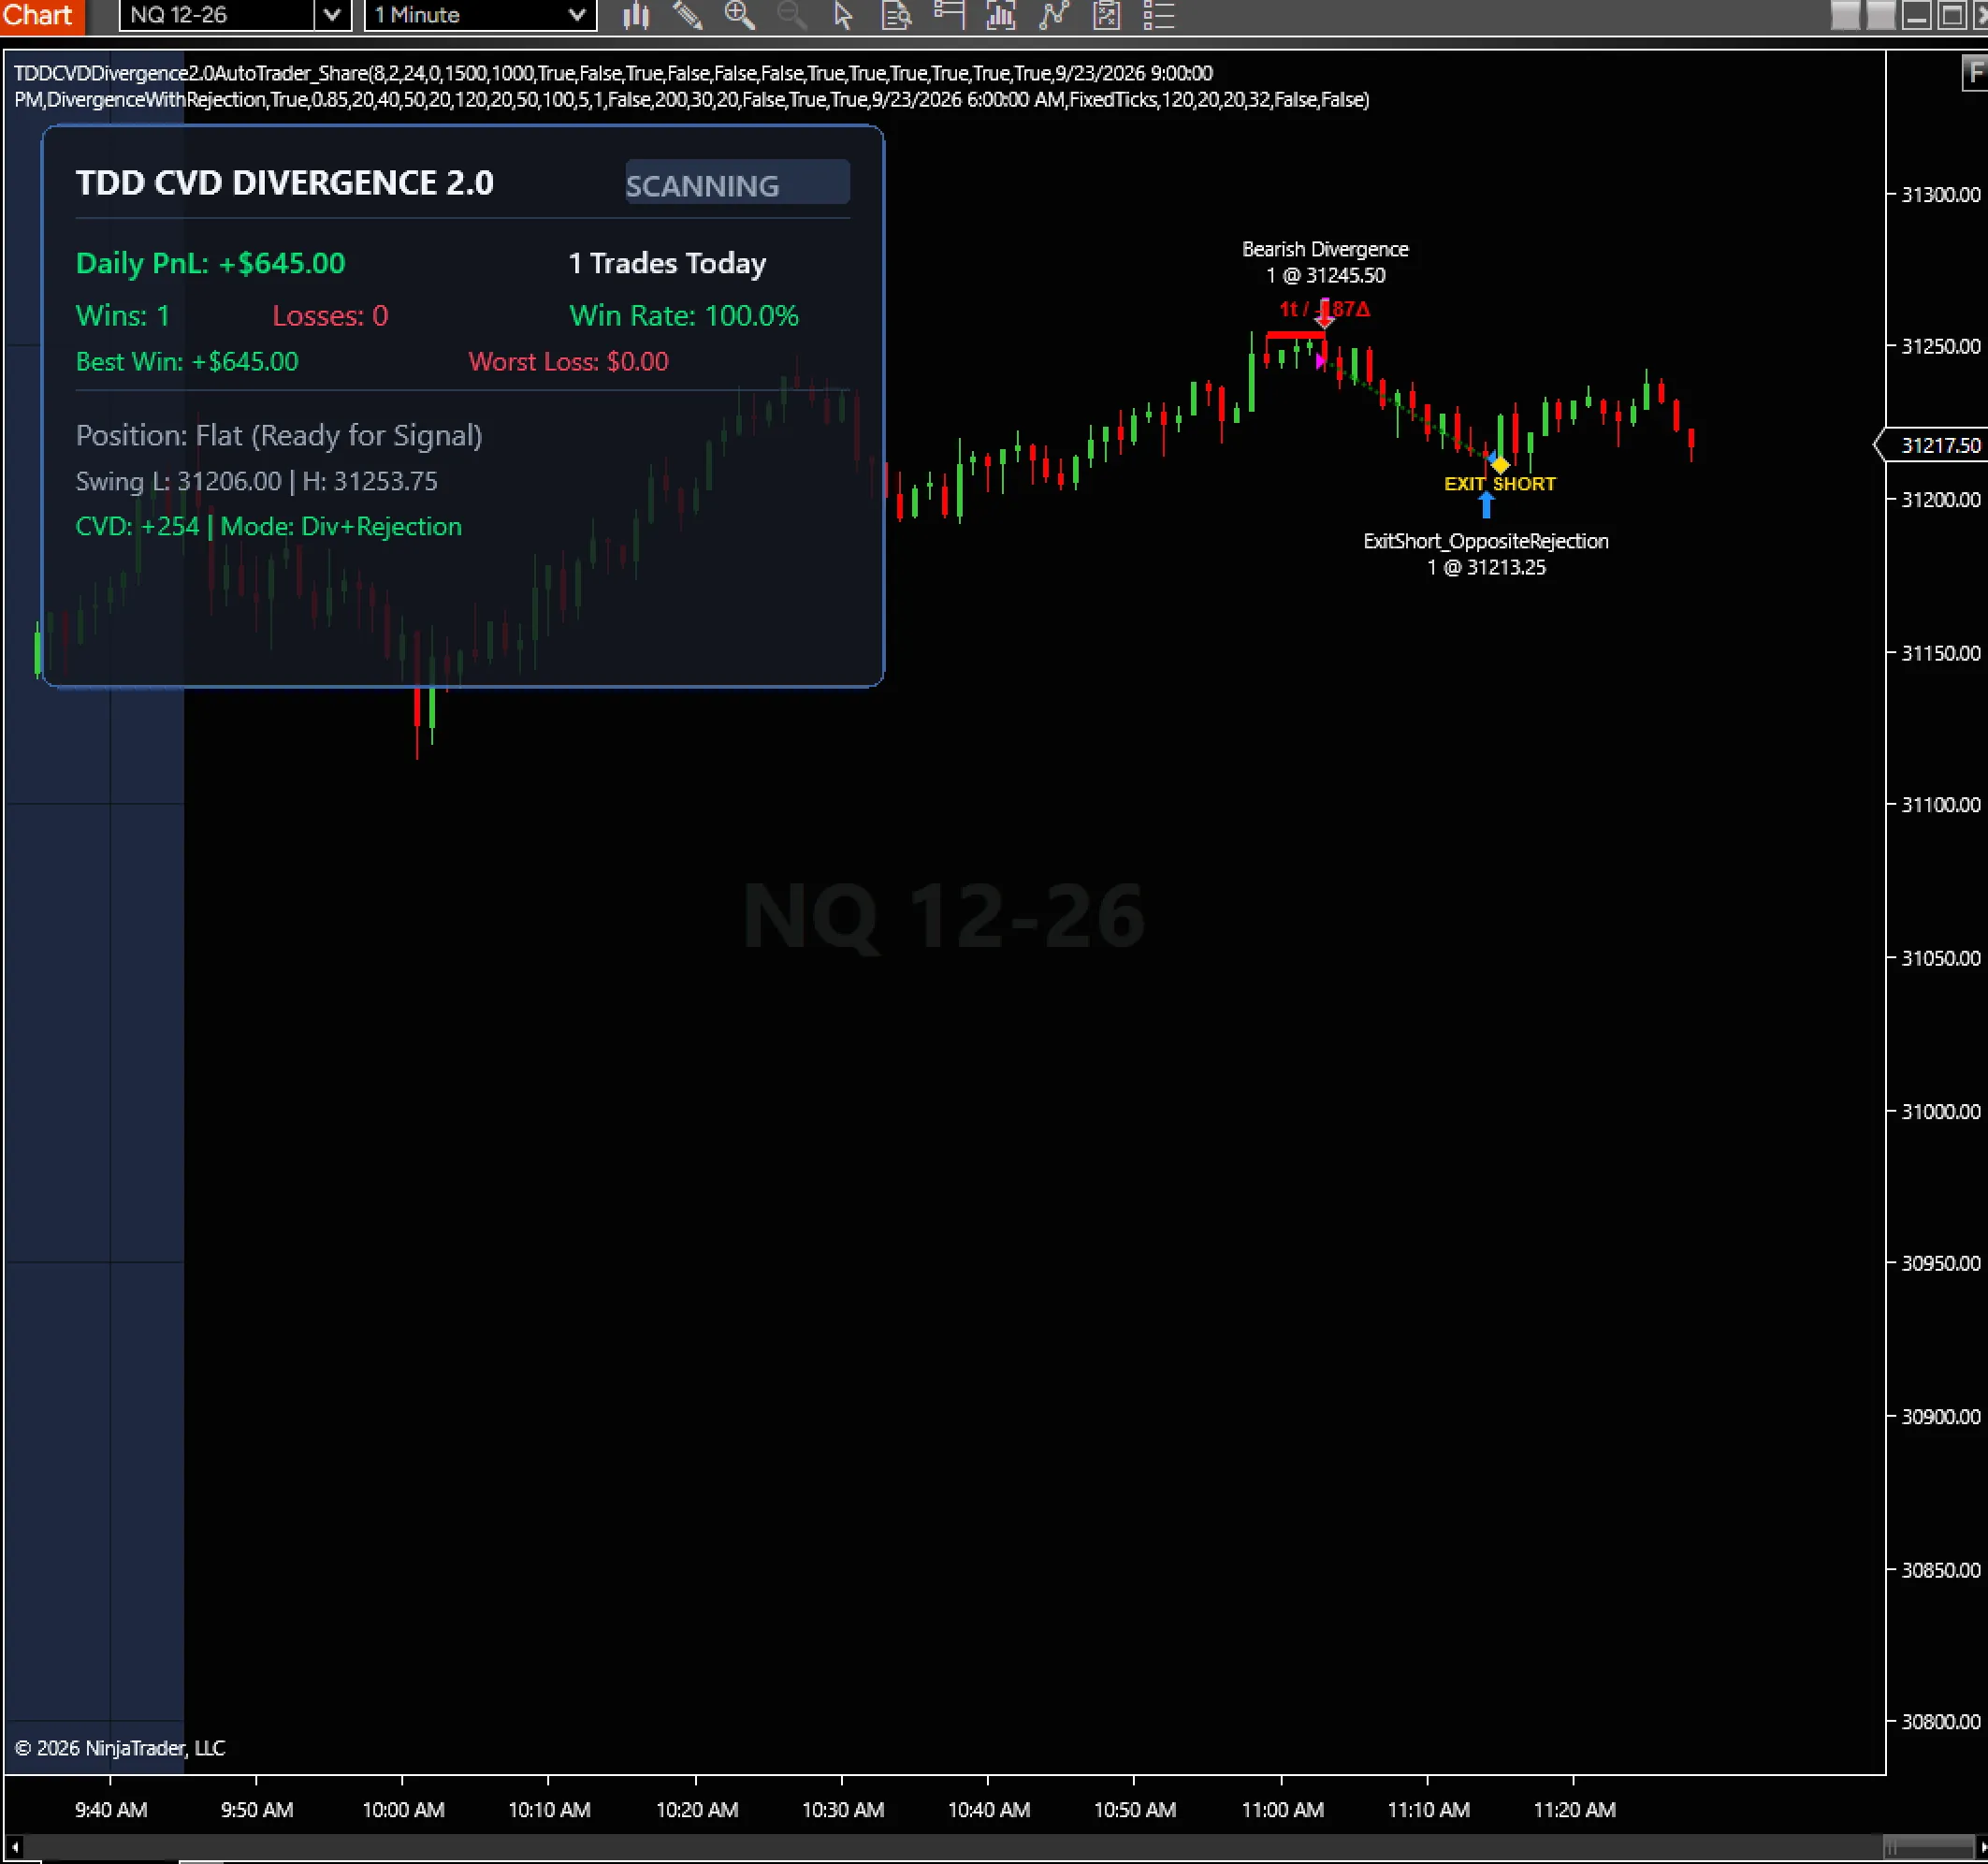
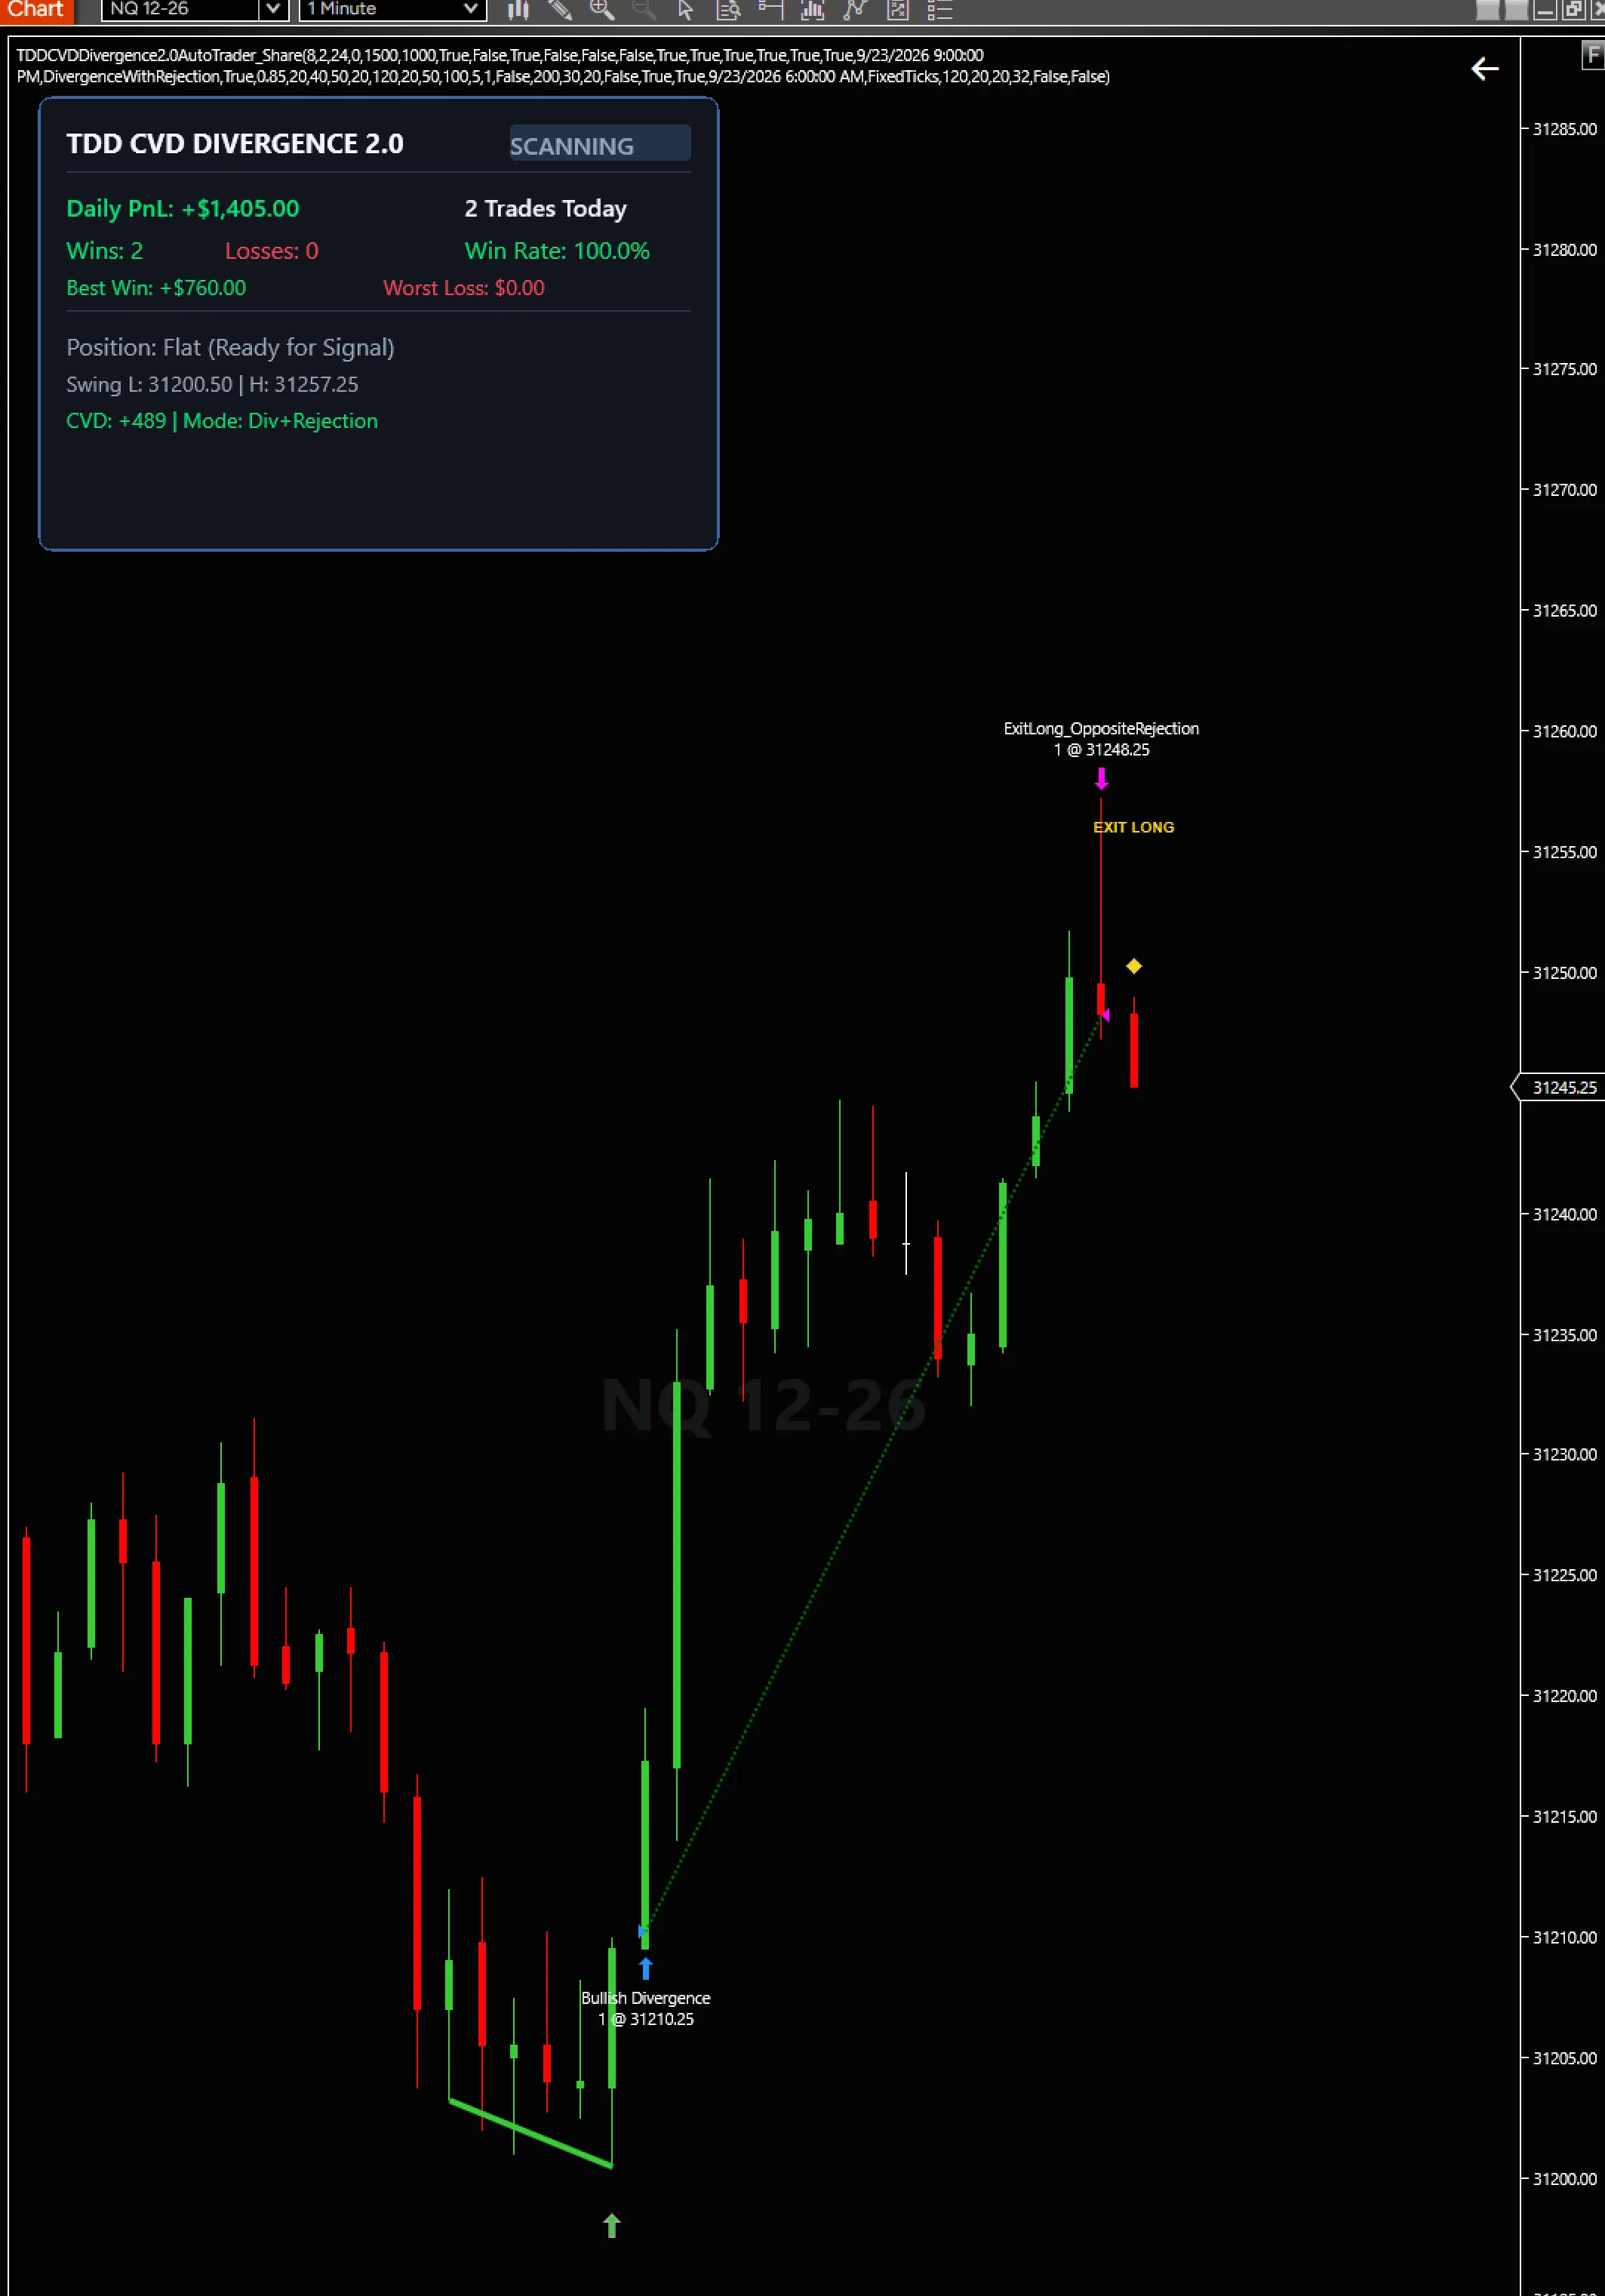
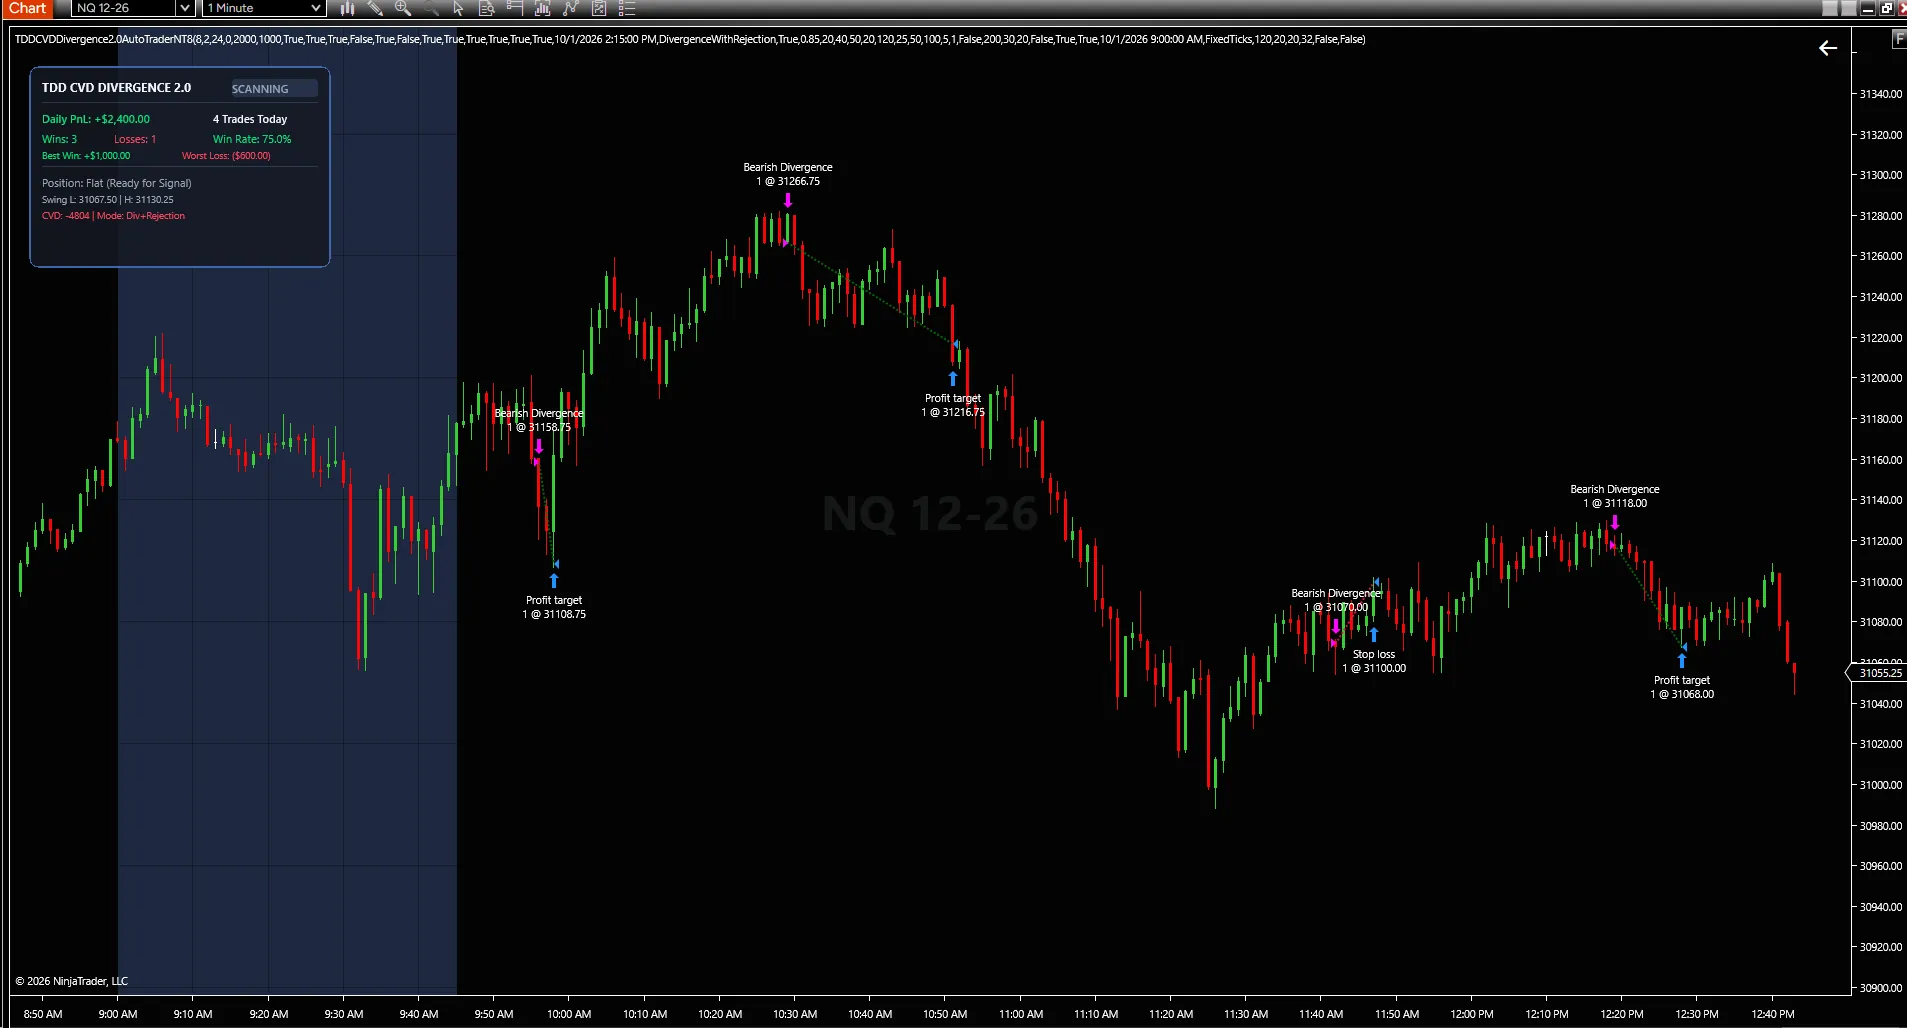
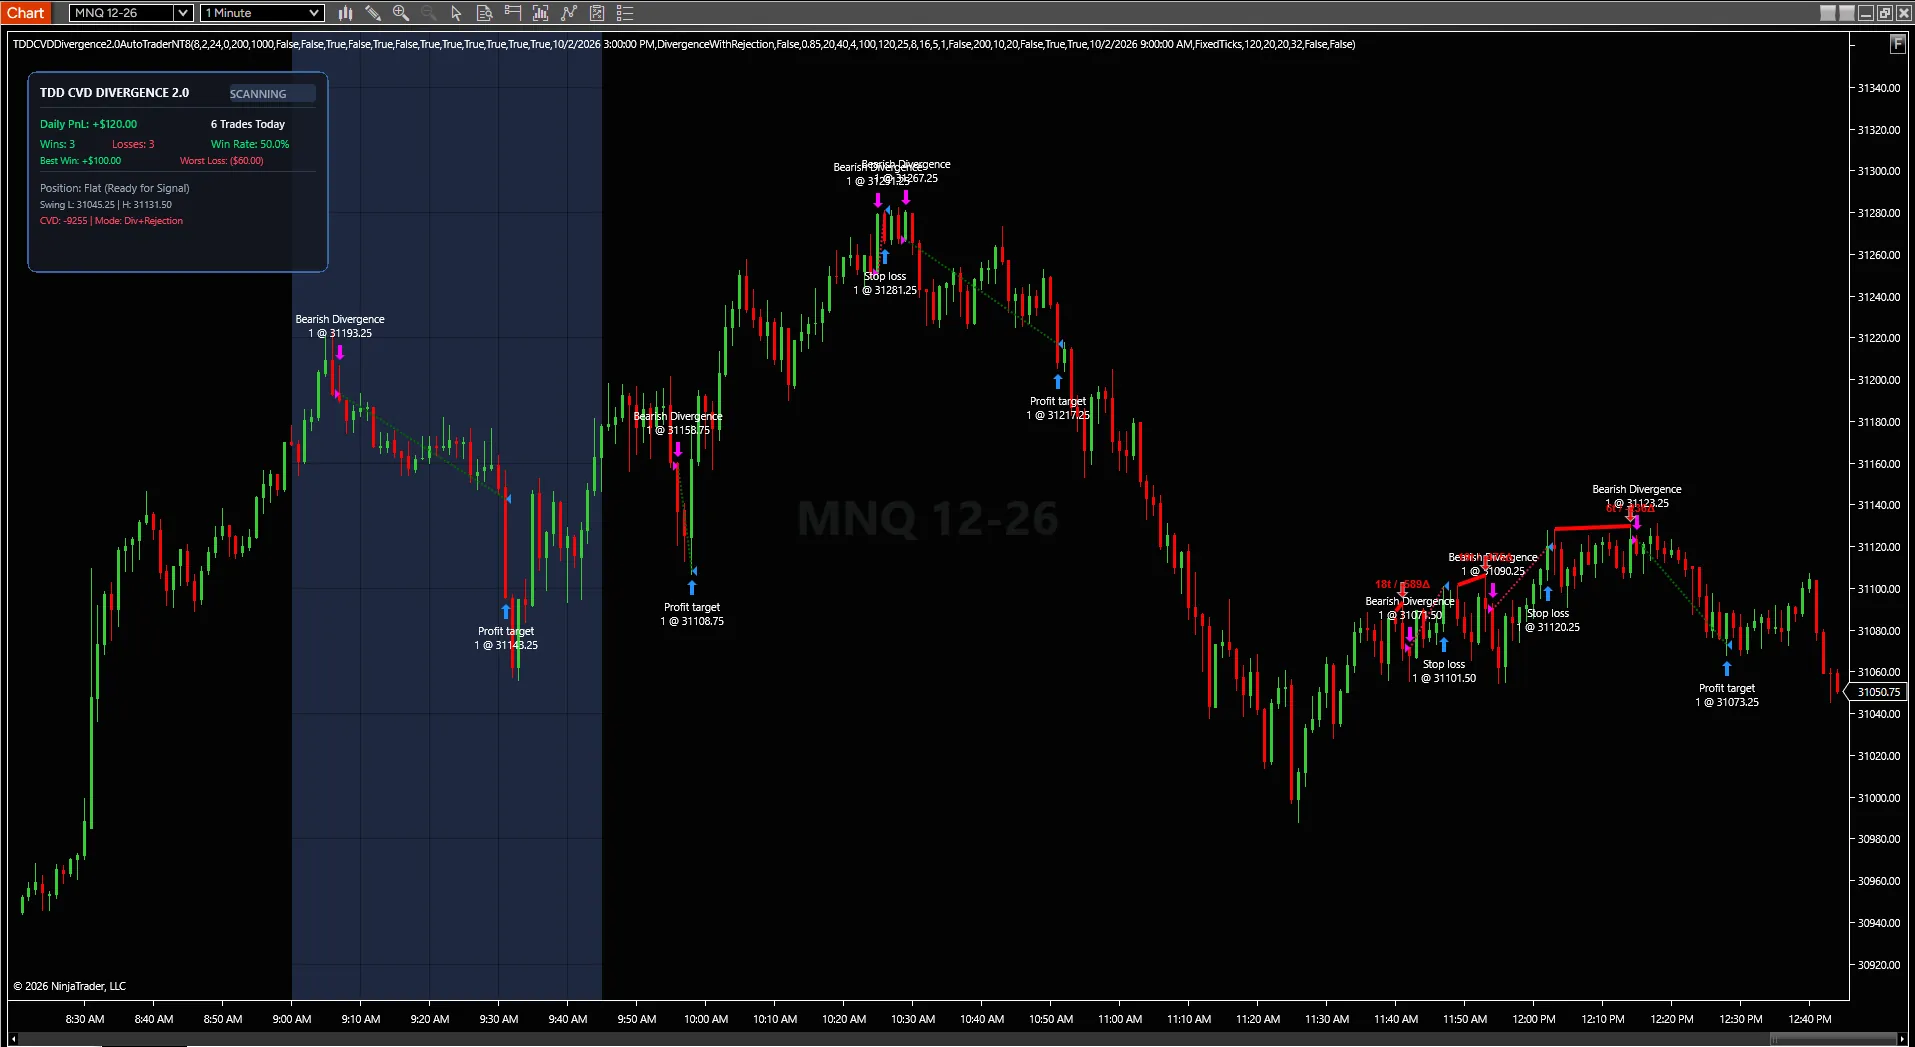
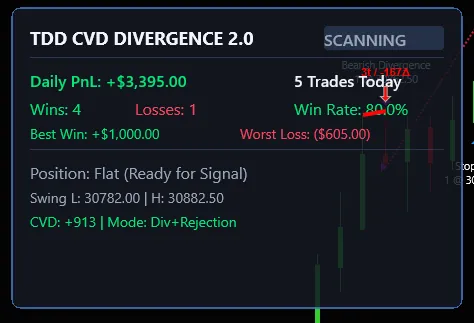
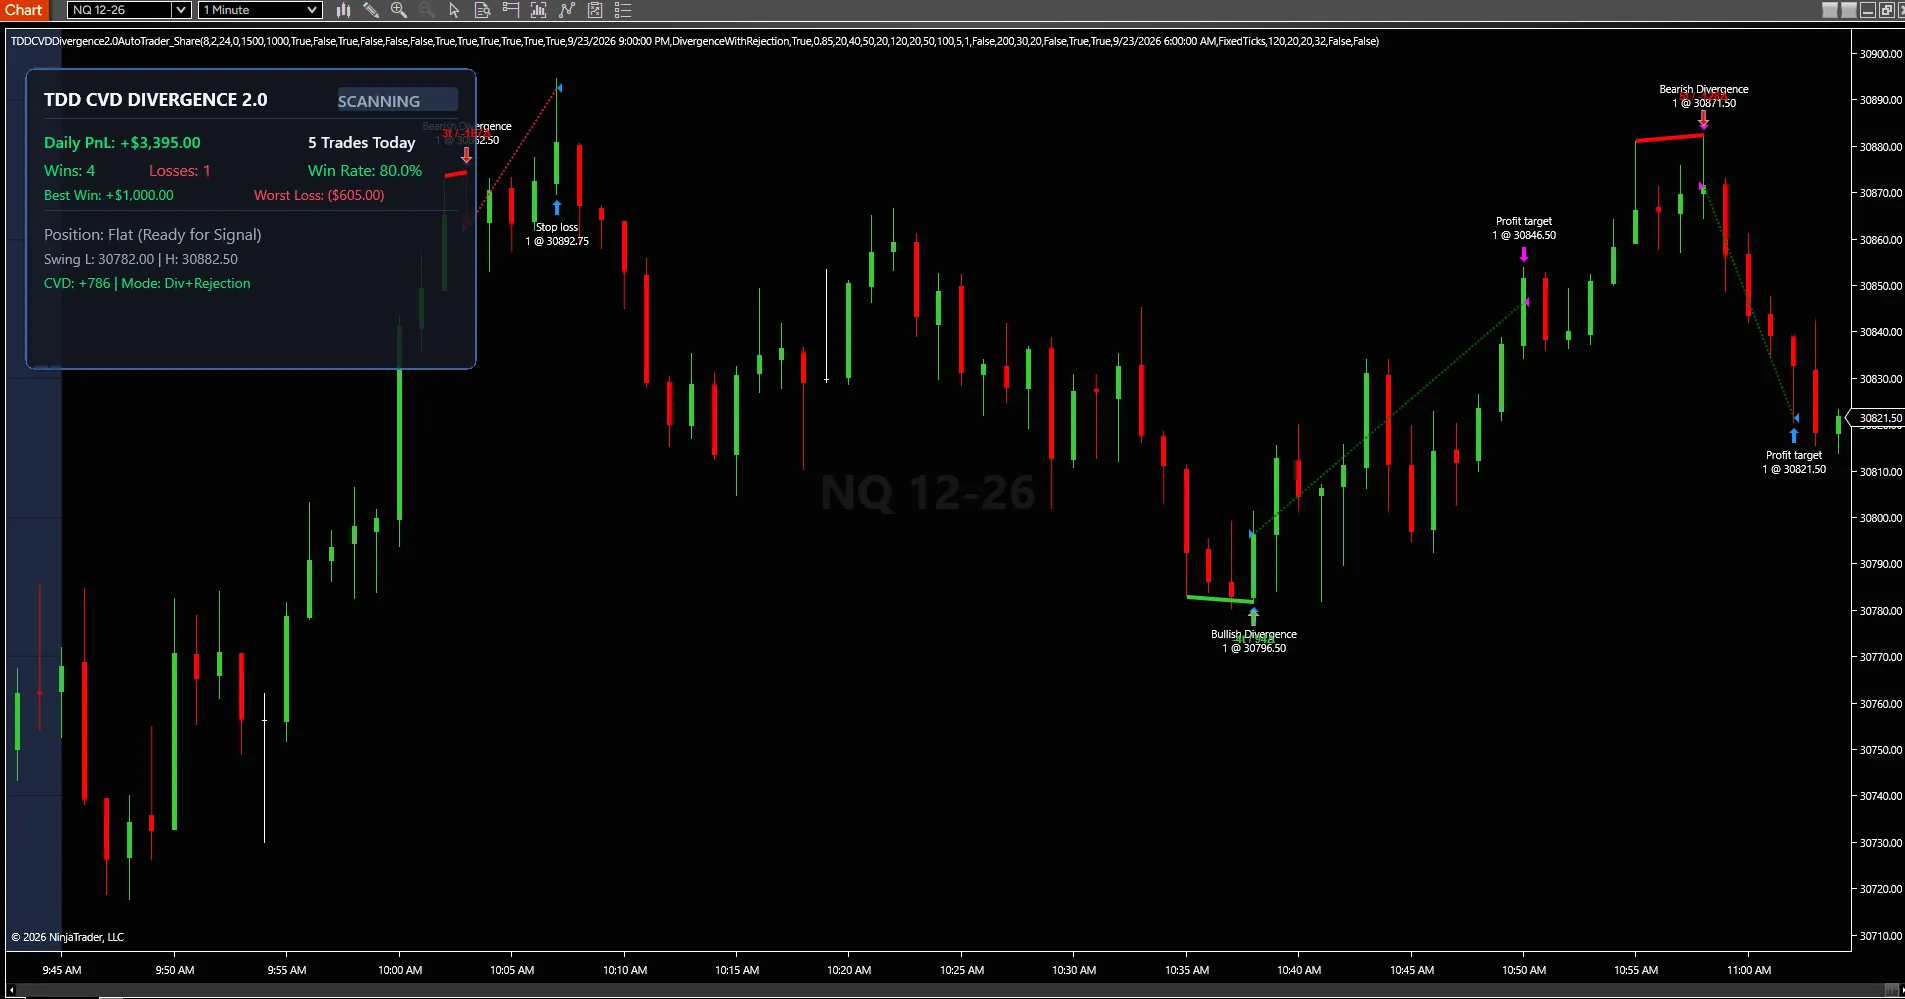
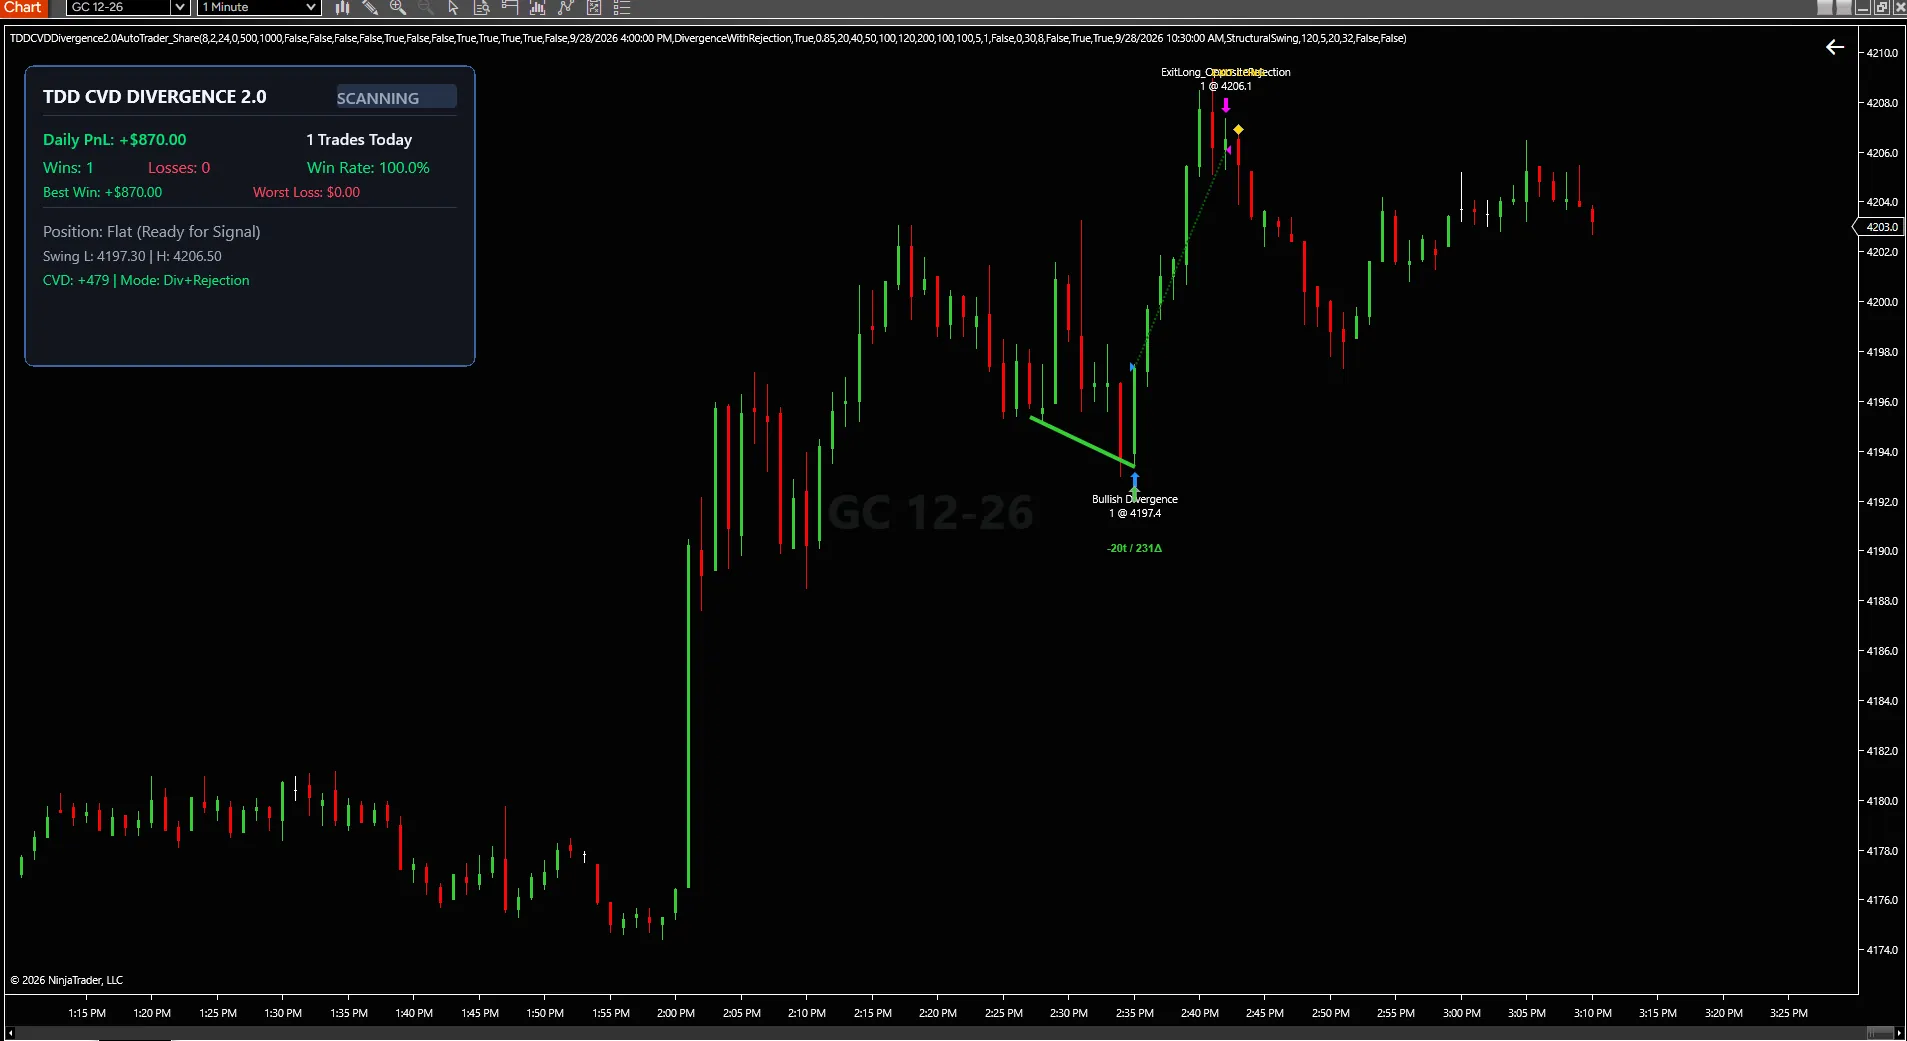
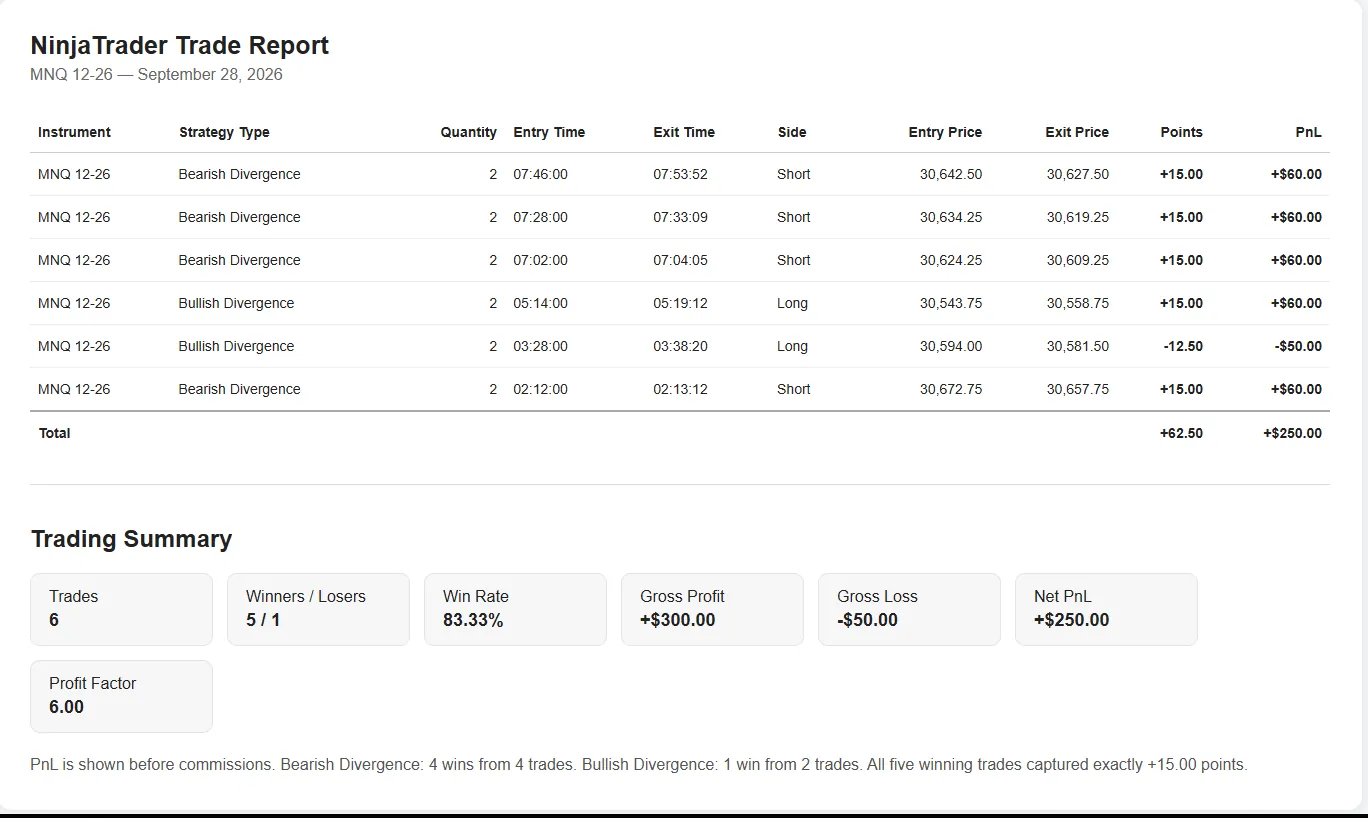
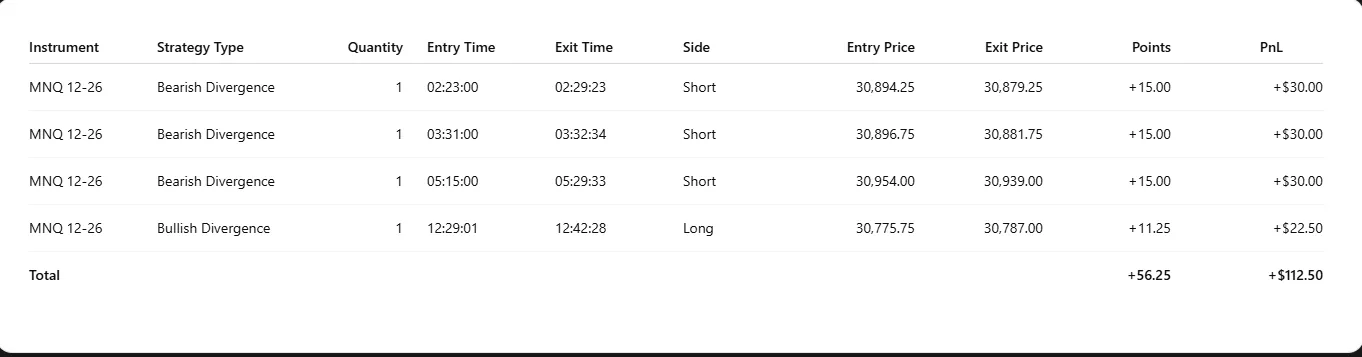
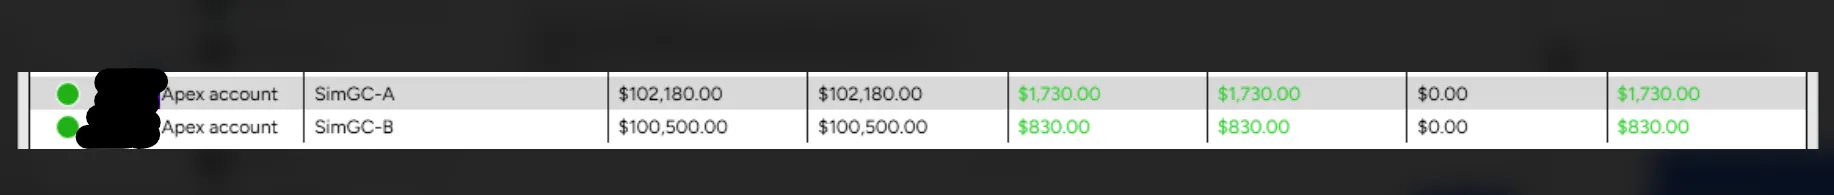
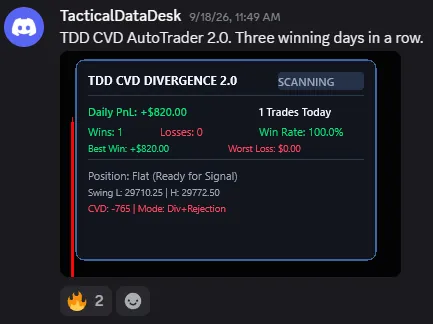
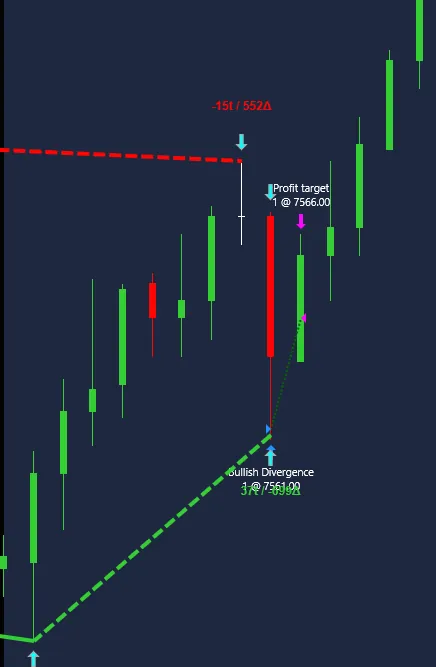
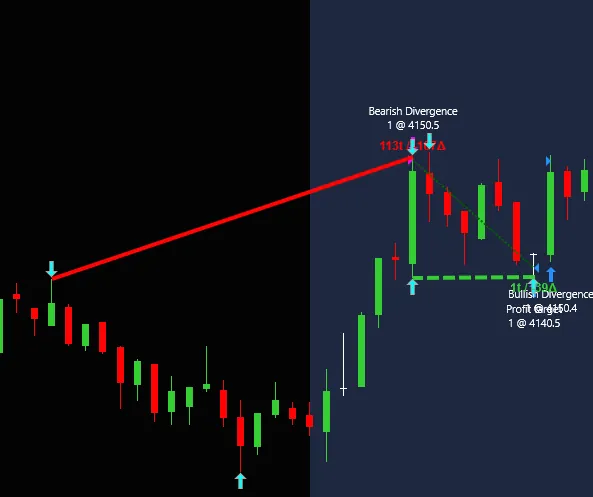
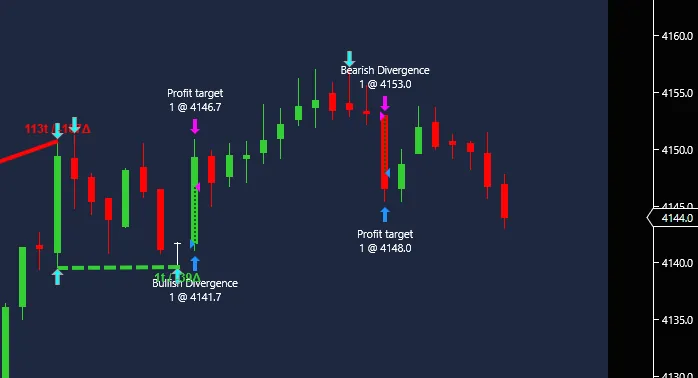
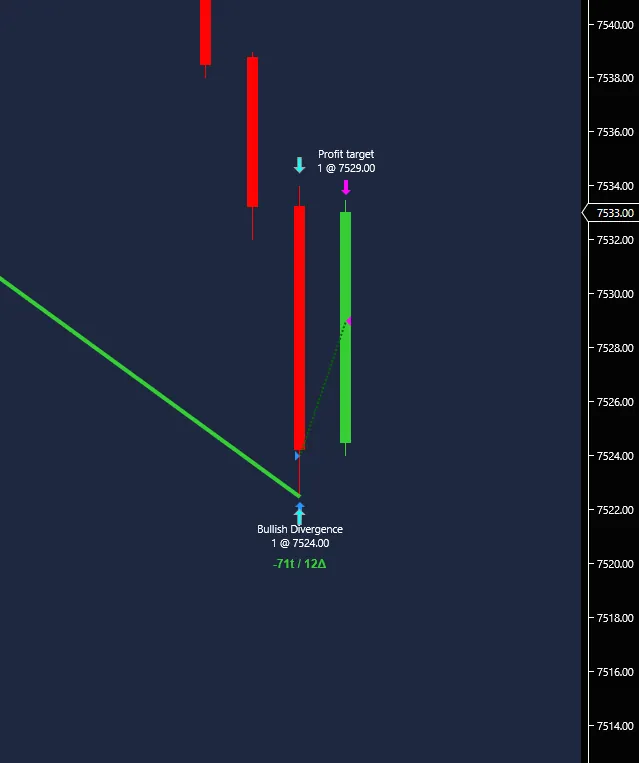
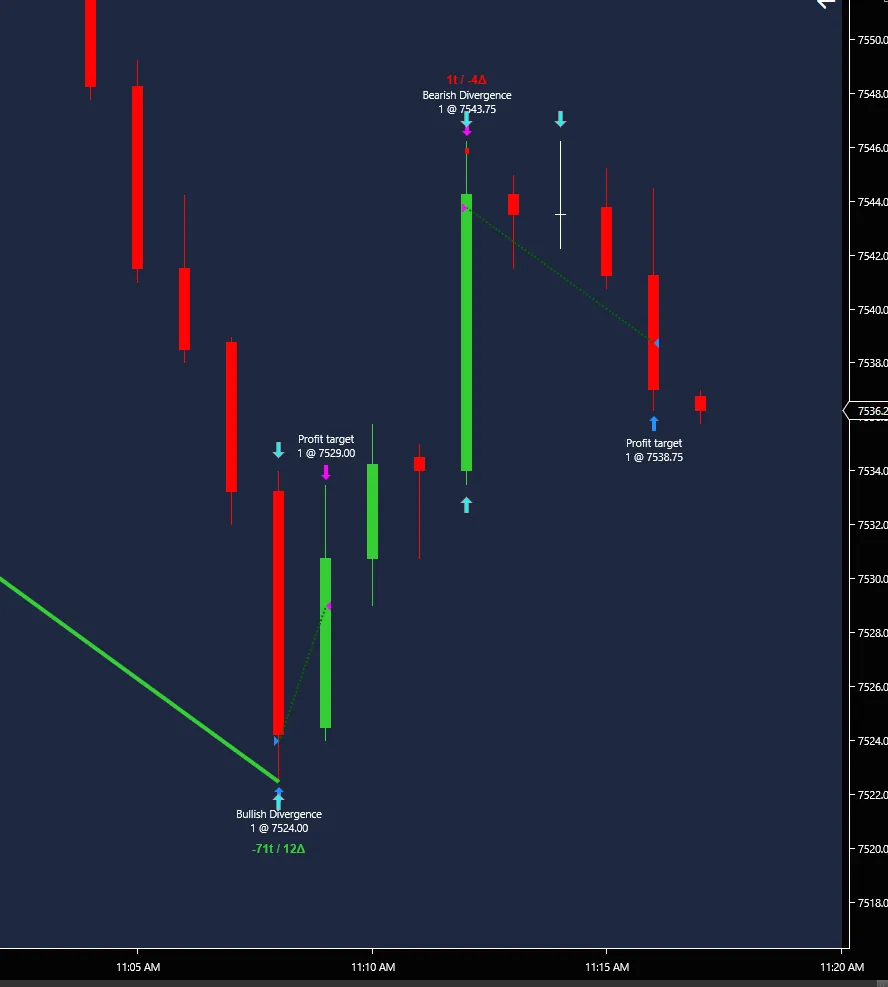
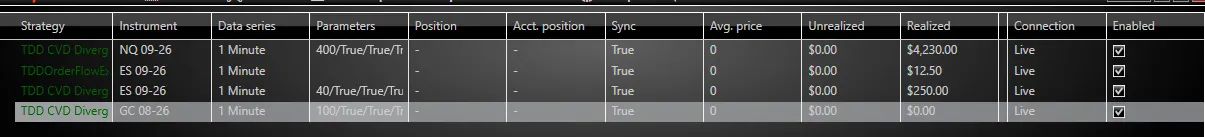
The AutoTrader tracks real-time Cumulative Volume Delta (CVD) against structural price swings, reading raw aggressive buying and selling volume to instantly spot institutional absorption.
Above or below the divergence lines, you will see a text print measuring the exact difference between the two swing pivots.
-52t means the second pivot was 52 ticks lower than the first).1499Δ means the aggressive buying was +1499 higher at the second pivot).Real results from the TDD community using the CVD Divergence AutoTrader.
Automate Your Edge at Mathematical Extremes.
Stop fighting the noise and let order flow automation do the heavy lifting.
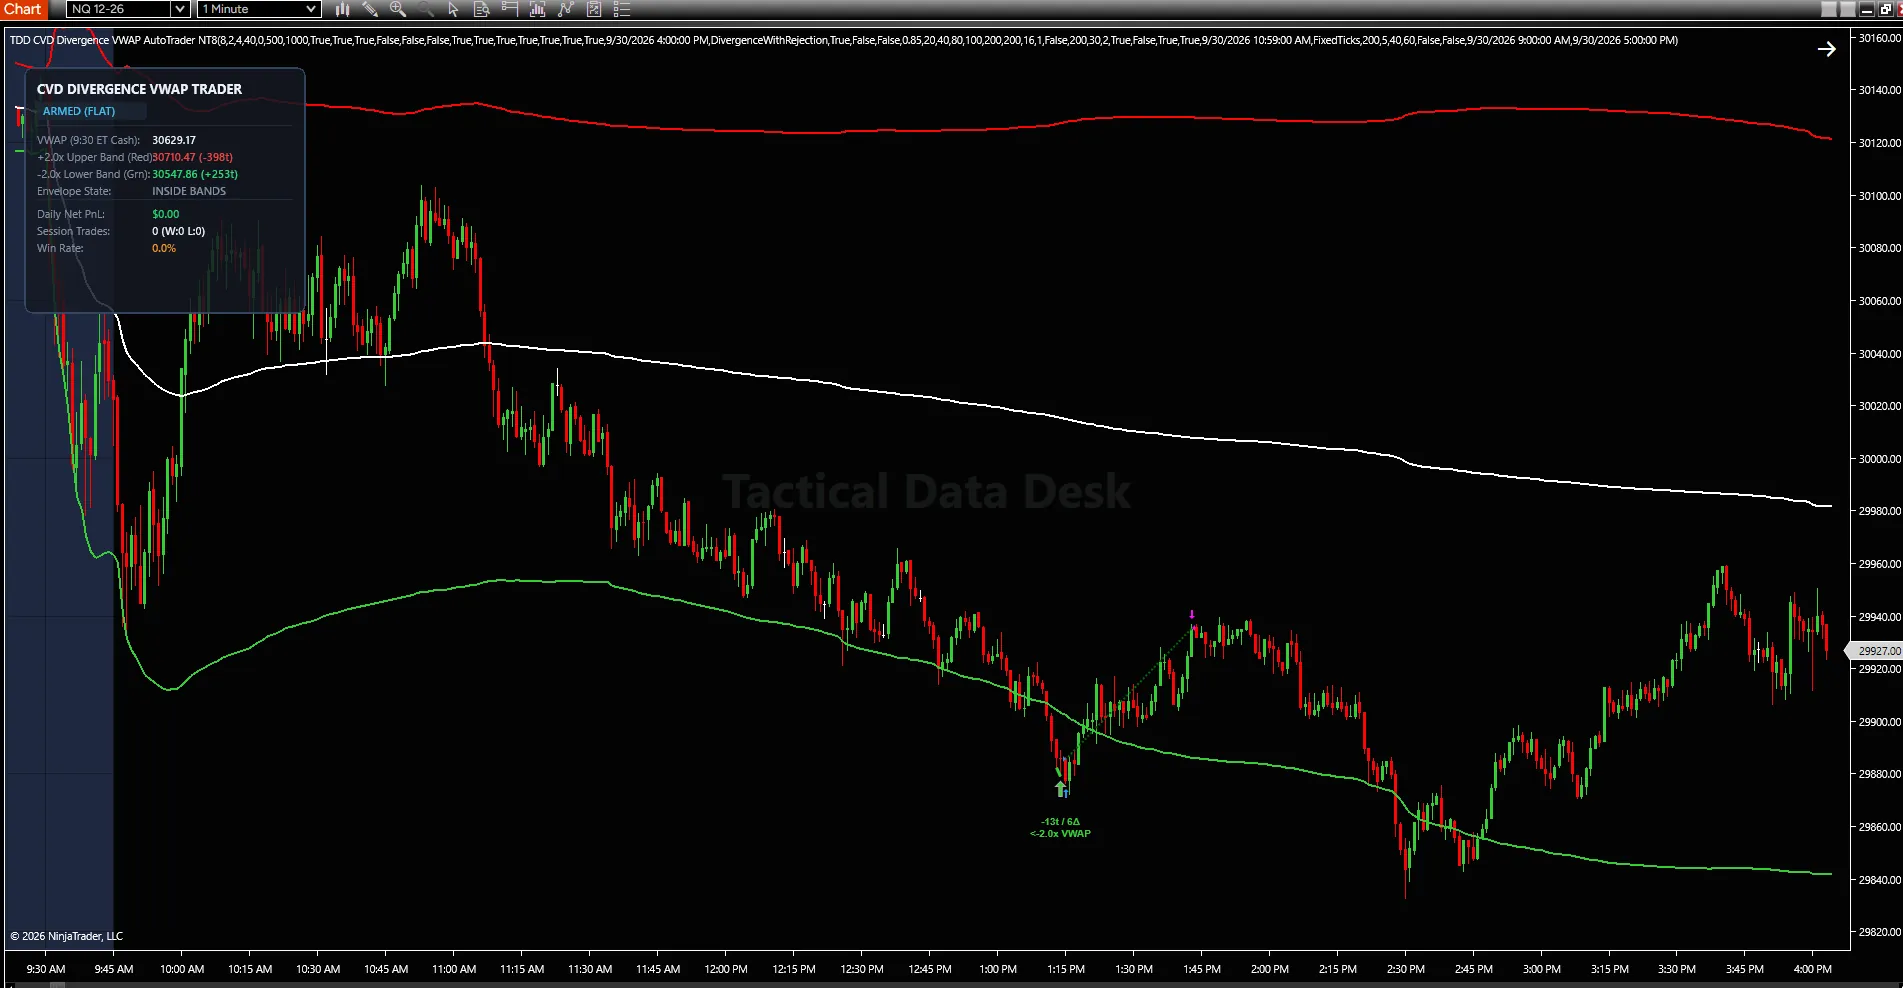
The TDD CVD Divergence VWAP AutoTrader NT8 is a completely hands-free, institutional-grade algorithm. It combines the raw, predictive power of Cumulative Volume Delta (CVD) Divergences with the precision of Anchored VWAP Standard Deviation Bands.
The result? A relentless mean-reversion engine that refuses to trade in the "choppy middle".
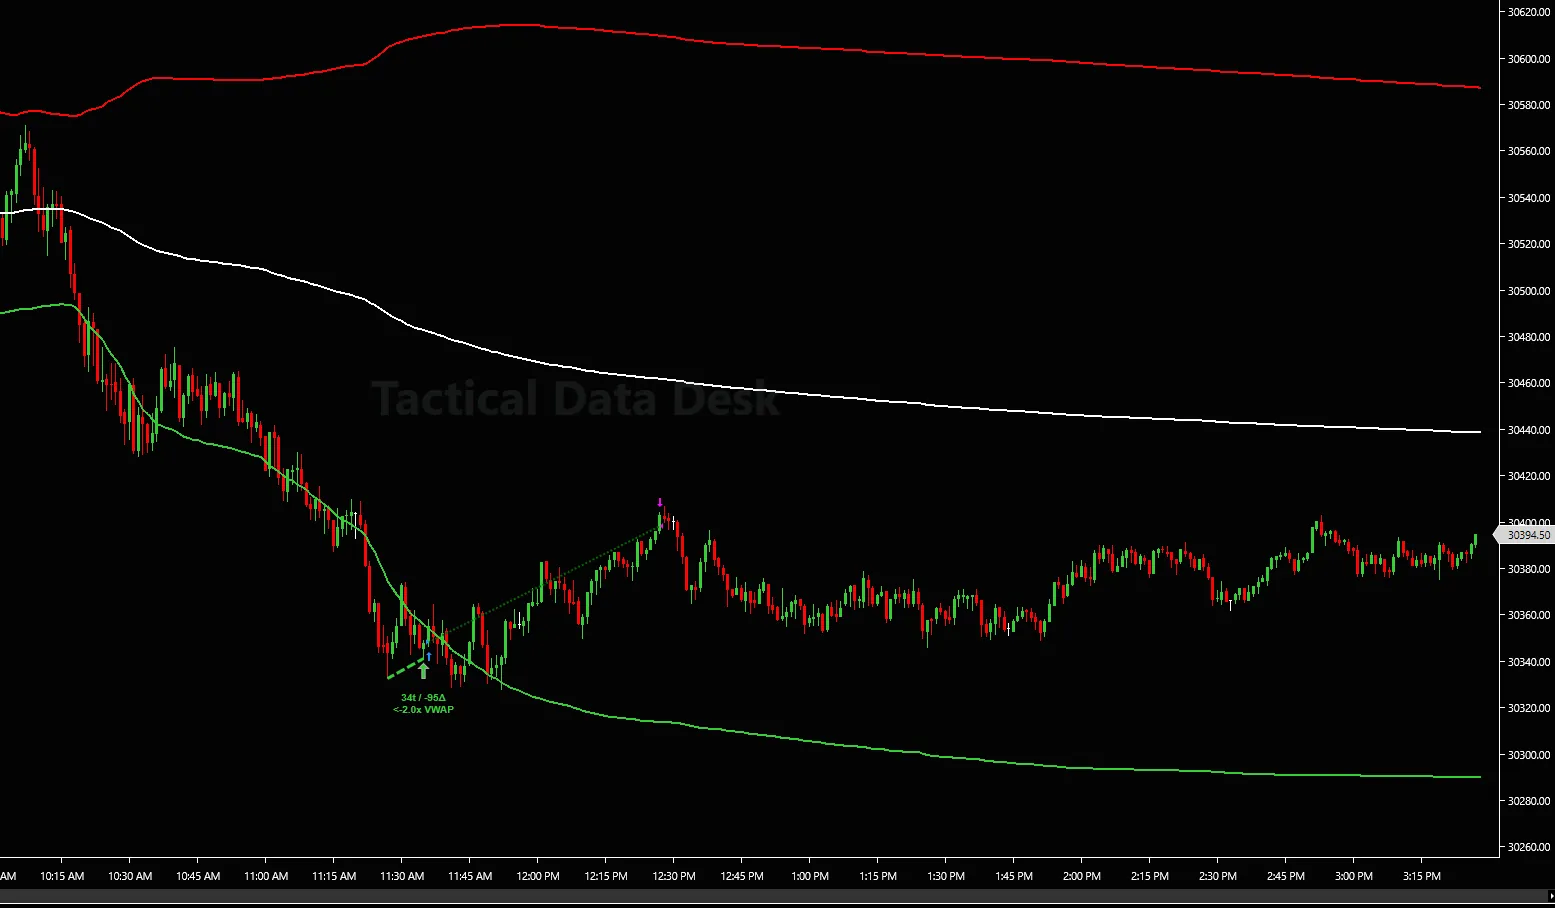
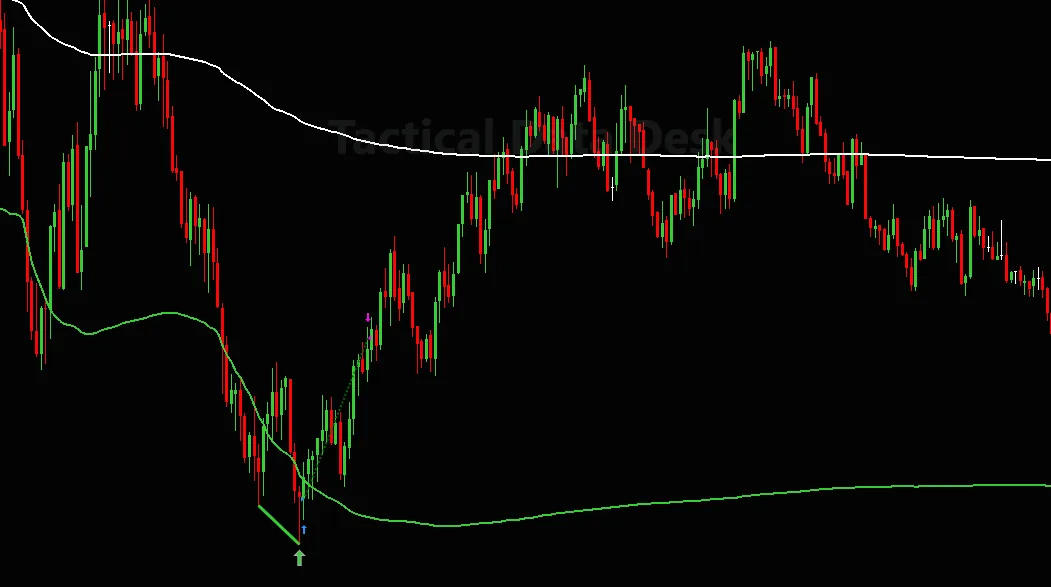
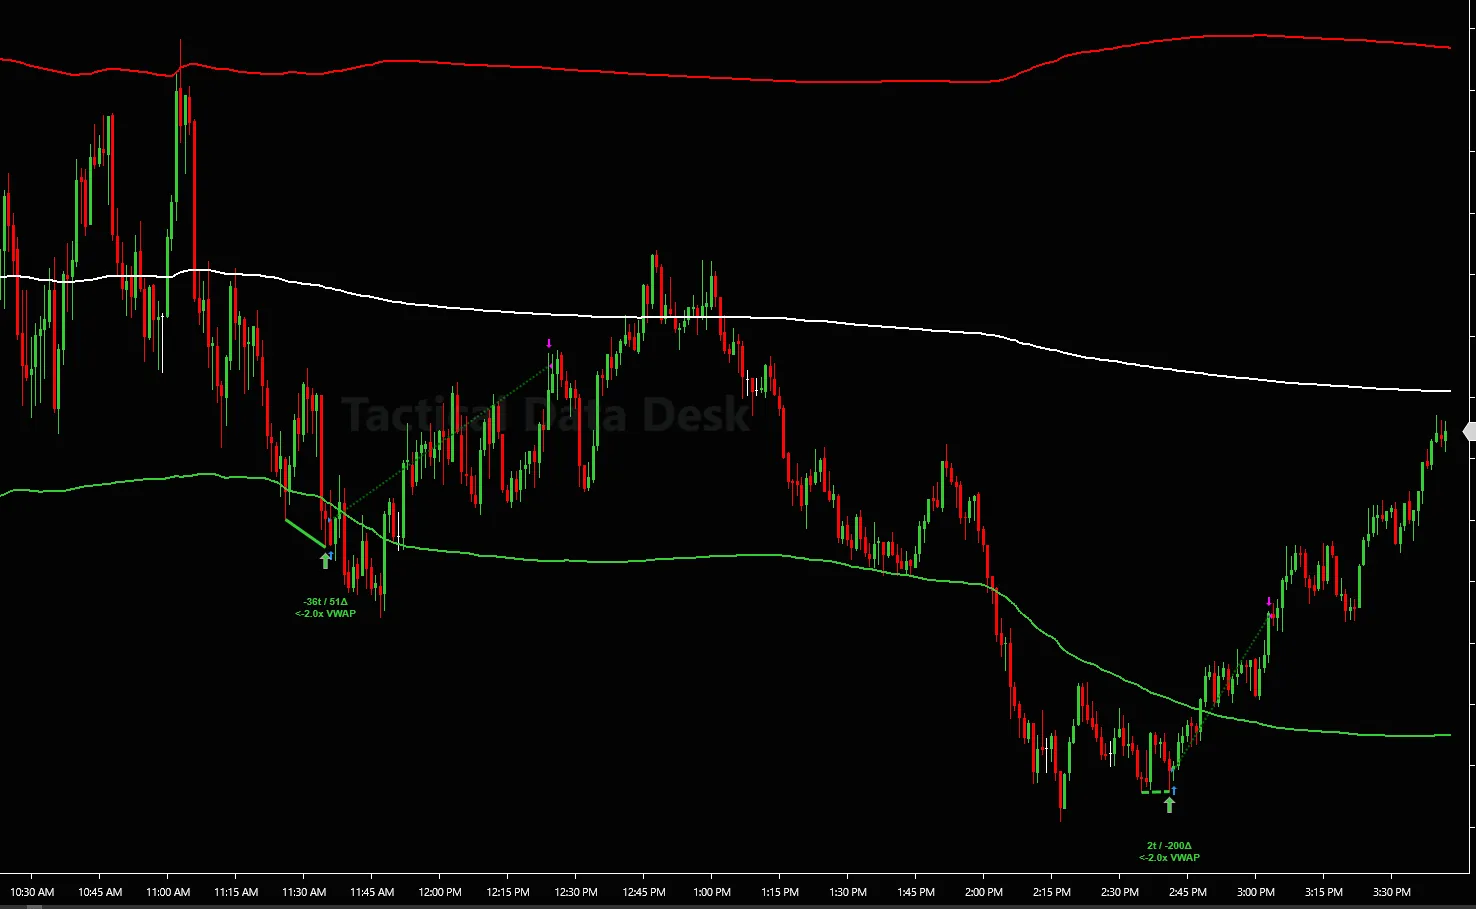
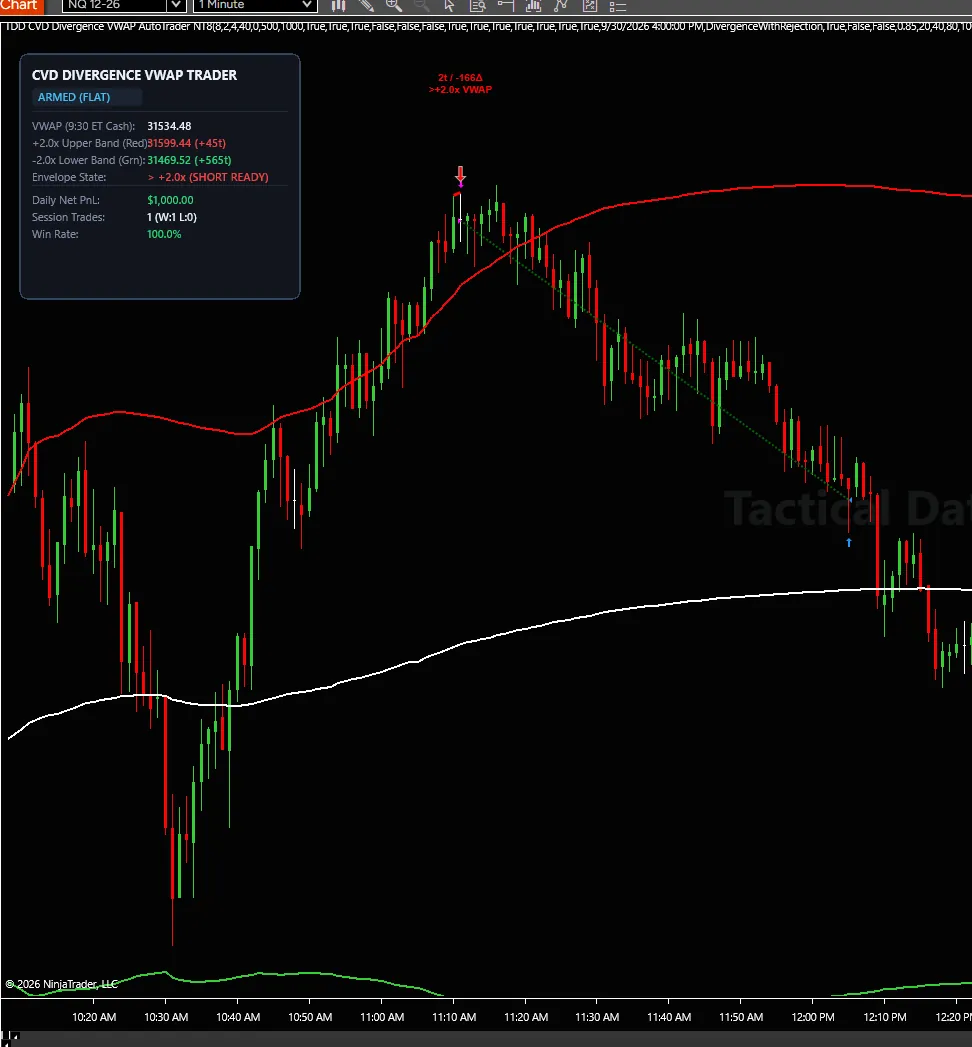
The algorithm waits patiently for price to stretch outside your custom VWAP Deviation Bands (e.g., 2.0x). Once over-extended, it scans the footprint. If a confirmed CVD Divergence combined with a candlestick rejection prints, it executes instantly—catching the "rubber band snap" back toward the mean.
Watch how the VWAP AutoTrader executes in real-time.